Finding the right Volvo is only one part of the vehicle-shopping process. You also need to decide how you want to pay for it, and for many drivers, that means choosing between financing and leasing.
Smythe Volvo NJ in Summit offers both financing and leasing resources to help qualified shoppers explore payment options for their next Volvo. Understanding how each option works can help you choose an approach that fits your budget, driving habits, and long-term plans.
Financing vs. Leasing: What Is the Difference?
Financing means borrowing money to purchase a vehicle. You make payments according to your loan agreement, and after the loan is fully paid, you own the vehicle.
Leasing is different. You generally pay to use the vehicle for an agreed period and mileage allowance rather than purchasing it outright at the beginning.
Both choices can make sense. The better option depends on your personal situation.
Why Consider Financing a Volvo?
Financing may be appealing if your goal is long-term vehicle ownership. Once the loan is paid off, the Volvo belongs to you, subject to the terms of your financing agreement.
Ownership also means you do not have the same end-of-lease mileage and vehicle-condition requirements that normally come with leasing.
For drivers who keep their vehicles for many years, financing may be worth considering.
Build Equity Through Vehicle Ownership
Each loan payment helps reduce the amount you owe on your vehicle. Over time, you may build positive equity if your Volvo is worth more than your remaining loan balance.
That equity can become useful when you eventually sell or trade the vehicle.
Keep in mind that vehicle values change over time. Age, mileage, condition, history, equipment, and market demand can all affect resale and trade-in value.
Financing May Work Better for High-Mileage Drivers
A vehicle lease generally includes mileage limits. Driving beyond the mileage allowed by your agreement can result in additional charges at lease-end.
Financing does not normally place a contractual limit on how many miles you can drive your own vehicle. This can make purchasing more attractive for drivers with long commutes or frequent road trips.
Higher mileage can still affect the vehicle’s future value and maintenance needs.
Why Consider Leasing a Volvo?
Leasing can appeal to shoppers who enjoy driving newer vehicles and expect their needs to change every few years.
Because a lease covers a defined term, it can provide a natural point to consider another vehicle when the agreement ends. You can then review the options available under your specific lease.
For some shoppers, this makes it easier to experience newer Volvo designs and technology more frequently.
Leasing Can Offer Payment Flexibility
Lease payments are calculated differently from traditional vehicle loans. Depending on the specific vehicle, terms, amount due at signing, and available programs, a lease may provide a different monthly payment structure than financing the same vehicle.
However, never compare options using the monthly payment alone.
Review the complete lease terms, including the amount due at signing, mileage allowance, term, fees, and potential lease-end costs.
Understand Lease Mileage Limits
Your driving habits are one of the most important factors when deciding whether to lease.
Lease agreements typically establish an allowed number of miles. If you drive more than the agreed amount, excess-mileage charges may apply when the vehicle is returned.
Before leasing, estimate your annual driving as accurately as possible. Consider your commute, family trips, vacations, and other regular travel.
Understand Vehicle Condition Requirements
A leased Volvo must generally be returned in a condition that meets the standards described in the lease agreement. Normal wear may be expected, but excess wear or damage can lead to additional charges.
Read the lease agreement carefully so you understand your responsibilities.
If you are unsure what qualifies as excess wear, ask the finance team to explain the applicable terms before signing.
Which Option Is Better for You?
There is no single answer that works for every driver. Your budget, driving habits, ownership goals, and vehicle preferences should guide your decision.
Financing may make sense if you:
- Want to own your Volvo
- Plan to keep it for many years
- Drive a high number of miles
- Prefer not to have lease-end mileage limits
- Want to build potential vehicle equity
Leasing may be worth considering if you:
- Prefer changing vehicles more frequently
- Drive a predictable number of miles
- Want a defined lease term
- Like exploring newer Volvo models regularly
- Are comfortable following lease return requirements
The finance professionals at Smythe Volvo NJ can help shoppers compare the available options for a particular vehicle.
Choose the Volvo That Fits Your Lifestyle
Before discussing payment options, decide which Volvo best matches your needs.
Smythe Volvo’s current lineup includes SUVs, plug-in hybrids, and fully electric models, along with the V60 Cross Country. Available models and inventory can change.
Think about passenger capacity, cargo space, daily mileage, parking, weather, and the features that matter most to you.
Consider Volvo SUVs
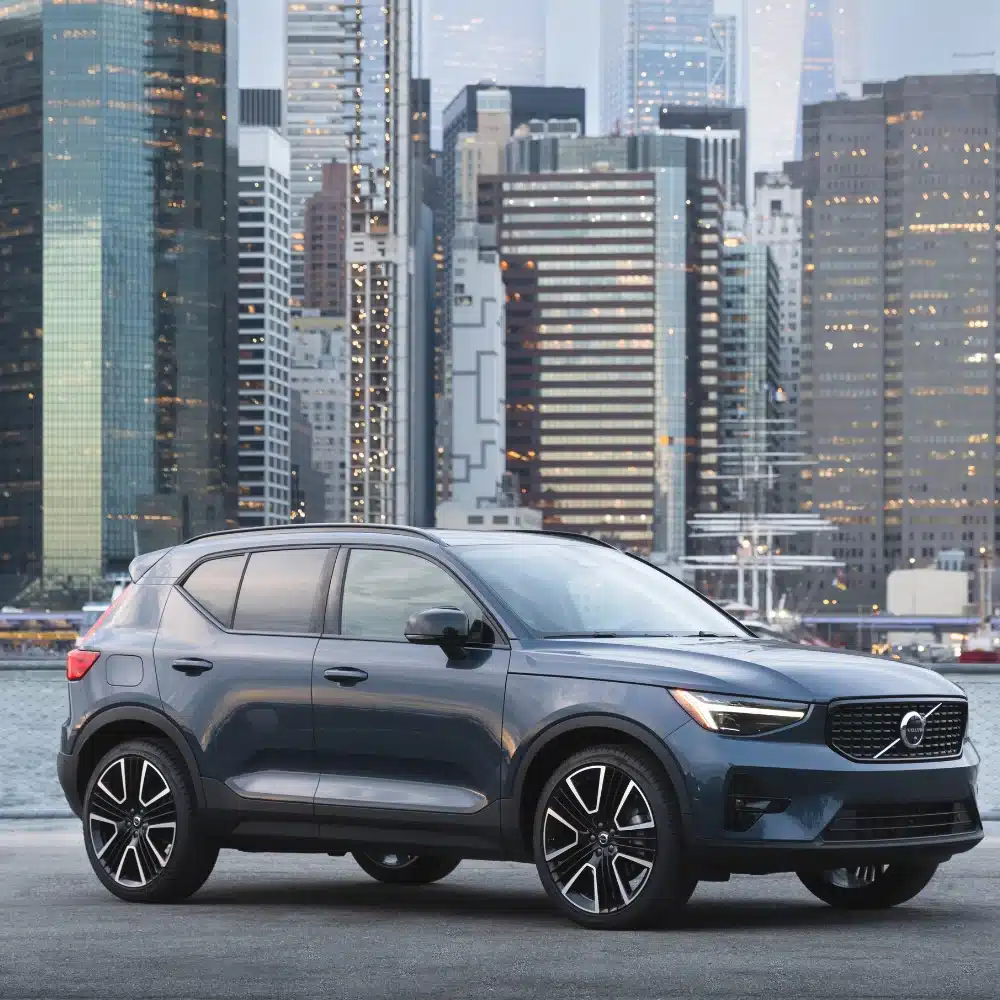
Volvo offers SUVs in several sizes. Shoppers can compare models such as the XC40, XC60, and XC90 depending on current availability.
A smaller SUV can be practical for commuting and parking. A larger model may be more appropriate for families needing additional passenger and cargo room.
Test-drive different sizes before deciding.
Explore Plug-In Hybrid Options
Drivers interested in electrified driving may consider a Volvo plug-in hybrid. Smythe Volvo’s current model lineup includes plug-in hybrid versions of the XC60 and XC90.
A plug-in hybrid combines an electric driving system with a gasoline engine. It can be worth considering if you have regular charging access but also want the flexibility of a gasoline engine.
Electric range and efficiency vary based on model, temperature, charging, driving habits, and other conditions.
Consider a Fully Electric Volvo
Smythe Volvo also offers access to fully electric Volvo models, depending on current inventory.
Before choosing an EV, think about your daily driving distance and charging options. Consider whether you can charge at home, at work, or through public charging stations.
Charging times and driving range can vary based on the model, charger, temperature, battery condition, and driving conditions.
Financing a New vs. Used Volvo
Financing is not limited to new vehicles. Smythe Volvo also offers pre-owned inventory, giving shoppers additional choices across different model years and price points.
Used-vehicle financing terms can differ from those offered for new vehicles. The vehicle’s age, mileage, purchase price, buyer qualifications, and lender requirements may affect available options.
Compare the complete financing terms before choosing.
Consider Certified Pre-Owned
A Certified Pre-Owned Volvo can provide another option for shoppers who want a pre-owned vehicle that meets applicable manufacturer certification requirements.
CPO vehicles must satisfy the requirements of the Certified by Volvo program. Warranty coverage and other program benefits can make CPO worth comparing with both new and traditional used vehicles.
If financing a CPO vehicle, ask whether any current financing programs apply to the specific Volvo you are considering.
Understand APR and Loan Terms
When financing, pay close attention to the annual percentage rate, or APR. The APR affects how much financing costs over the life of your loan.
The loan term matters too.
A longer loan can reduce your monthly payment but may increase the total interest you pay. A shorter term may create a higher monthly payment while potentially reducing total interest.
Compare both monthly affordability and overall cost.
Think Carefully About Your Down Payment
A down payment reduces the amount you need to finance. The appropriate amount depends on your budget, available cash, loan terms, and other financial priorities.
Do not automatically use all your available savings for a vehicle down payment.
Review your complete financial situation and choose an amount you are comfortable paying.
Use Your Trade-In Toward Your Next Volvo
If you currently own a vehicle, a trade-in may help with your next purchase or lease. Smythe Volvo provides trade-in resources for shoppers considering an upgrade.
Your vehicle’s appraised value can depend on:
- Age
- Mileage
- Mechanical condition
- Exterior condition
- Interior condition
- Vehicle history
- Equipment
- Current market demand
If you still have a loan, obtain your payoff amount. This helps determine whether you have positive or negative equity.
What If You Have Negative Equity?
Negative equity means your loan payoff is higher than the vehicle’s trade-in value.
For example, if your payoff is $20,000 and your vehicle is worth $17,000, there is a $3,000 difference.
Depending on lender approval and transaction terms, negative equity may need to be paid separately or included in new financing. Adding it to another loan increases the amount financed and can increase your overall borrowing cost.
Apply for Financing Online
Smythe Volvo NJ provides an online finance application that can help shoppers begin the process before visiting the Summit dealership.
According to Smythe Volvo, shoppers can submit information through the online application for a vehicle purchase or lease. A member of the finance team can then review available options.
Approval and terms depend on credit and other applicable requirements.
Step-by-Step Guide to Financing or Leasing Your Volvo
A simple process can make the financial side of vehicle shopping easier to understand.
Step 1: Set a Comfortable Budget
Determine what you can reasonably afford.
Remember to consider insurance, fuel or charging, maintenance, registration, and other vehicle expenses in addition to the monthly payment.
Step 2: Choose Your Volvo
Compare vehicles based on size, passenger room, cargo space, powertrain, technology, and price.
Schedule a test drive before making your final decision.
Step 3: Decide Between Financing and Leasing
Think about how long you want to keep the vehicle and how many miles you normally drive.
If long-term ownership matters most, financing may fit your goals. If you prefer a defined term and regularly changing vehicles, leasing may be worth considering.
Step 4: Value Your Trade
Request an appraisal if you have a vehicle to trade.
Compare the appraised value with any outstanding loan payoff.
Step 5: Complete a Finance Application
Use Smythe Volvo’s online application or work with the finance department at the dealership.
Provide accurate information so available options can be reviewed.
Step 6: Compare the Complete Terms
For financing, review the APR, loan term, down payment, amount financed, monthly payment, and total estimated interest.
For leasing, review the term, mileage allowance, amount due at signing, monthly payment, fees, and lease-end requirements.
Step 7: Ask Questions
Do not sign anything you do not understand.
Ask the finance team to explain unfamiliar terms, fees, optional products, or conditions.
Step 8: Review the Final Agreement
Carefully read the complete agreement before signing.
Make sure the vehicle, price, trade value, financing or lease terms, taxes, fees, and other conditions match what you agreed to.
Make Your Next Volvo More Accessible
Choosing between financing and leasing does not need to be confusing. Understanding how each option works can help you select an approach that fits your budget, driving habits, and plans for the future.
At Smythe Volvo NJ, shoppers can explore new and pre-owned Volvo vehicles while working with the dealership’s finance team to review available loan and lease options. Compare the complete terms carefully, choose the Volvo that fits your lifestyle, and make a payment decision based on both your monthly budget and long-term goals.
Frequently Asked Questions
Does Smythe Volvo offer financing and leasing?
Yes. Smythe Volvo Cars provides financing resources for shoppers considering vehicle loans and Volvo leases. Approval, rates, and terms depend on buyer qualifications, the vehicle, and applicable programs.
Is it better to finance or lease a Volvo?
It depends on your needs. Financing can be attractive if you want long-term ownership, while leasing may appeal to drivers who prefer a defined term and the opportunity to change vehicles more frequently.
Can I apply for Volvo financing online?
Yes. Smythe Volvo provides an online finance application that can be used to begin the financing or leasing process before visiting the dealership.
Can I trade in my current vehicle?
Yes. Smythe Volvo offers trade-in resources. Your vehicle’s value can depend on its age, mileage, condition, history, equipment, and current market demand.
What should I compare when financing a Volvo?
Compare the APR, loan term, down payment, amount financed, monthly payment, applicable fees, and total estimated interest. Looking at the complete cost provides more information than comparing monthly payments alone.
What should I check before leasing a Volvo?
Review the lease term, mileage allowance, monthly payment, amount due at signing, fees, vehicle-condition requirements, excess-mileage charges, and lease-end options. Make sure the mileage allowance matches your driving habits.
Where can I finance or lease a Volvo in Summit, NJ?
Drivers researching Smythe Volvo NJ can visit Smythe Volvo Cars at 40 River Road in Summit, New Jersey. The dealership provides financing and leasing resources for qualified Volvo shoppers and offers an online finance application to help customers begin the process before their visit.